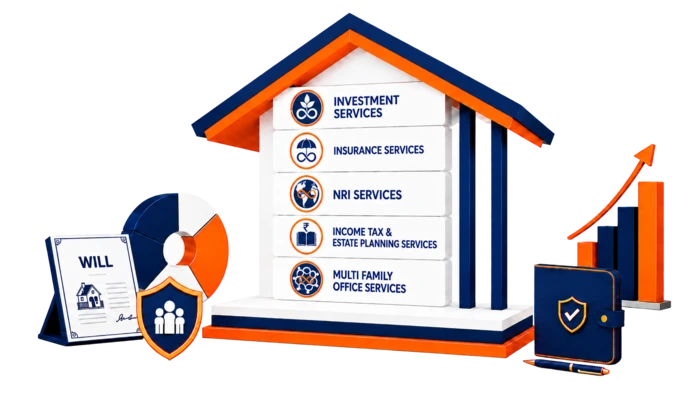
Everything about
Wealth…Investments
All in one place

  • Investments
  • Insurance
  • Taxation
  • Estate Planning
  • NRI Finances

India’s Trusted Financial Advisory Firm

Hero banner
Years
Legacy
0 +
Satisfied
Clients
0 +
Country
Clientele
0 +
Assets Under
Management (INR)
0 Cr+
Team
Members
0 +
Years Legacy
0 +
Satisfied Clients
0 +
Country Clientele
0 +
Assets Under Management (INR)
0 Cr+
Team Members
0 +

360 degree wealth management

End-to-end Financial Solutions

Comprehensive financial solutions to grow your wealth, protect your assets, optimize taxes, and secure your legacy.

Single Point of Contact

One Relationship Manager coordinates every financial need, ensuring seamless execution, advice and convenience.

Dedicated Team of Experts

Access Specialized Teams for every financial need, delivering expertise, seamless execution & trusted advice.

Complete Portfolio Audit at Zero Charge

Identify gaps, overlaps and opportunities across investments, insurance, taxes and your overall financial structure.

Value-Added Services Without Paying Extra

Individual Service Charges

Other service providers bill you separately for each service, making you pay more at extra costs.

Taxation Planning
Taxation Planning
  • Income Tax Filings and compliances
  • International Tax Reporting
  • HUF Planning
Extra Cost
Will Planning
Estate Planning
  • Will Planning
  • Private Family Trust
Extra Cost
Personal Accounting
Personal Accounting
Extra Cost
Auditing
Auditing
Extra Cost
CA Certifications
CA Certifications
Extra Cost

Exclusive Benefits with Ashutosh Financial Services

₹0 Additional Professional Charges
For Clients Availing Investment & Insurance Services
Taxation Planning
Taxation Planning
  • Income Tax Filings and compliances
  • International Tax Reporting
  • HUF Planning
✓ Included
Will Planning
Estate Planning
  • Will Planning
  • Private Family Trust
✓ Included
Personal Accounting
Personal Accounting
✓ Included
Auditing
Auditing
✓ Included
CA Certifications
CA Certifications
✓ Included
For Investment and Insurance Offerings, Ashutosh Financial Services receives brokerage/commission from product providers, including Asset Management Companies (AMCs) and Insurance companies, in accordance with applicable regulatory guidelines. The complimentary services offered by us are provided without any separate service fee and are subject to meeting the minimum investment / insurance criteria specified by us, which enable us to offer these services on a commercially sustainable basis.

Start your financial Journey with us

Achieving financial stability begins with the right advice. Our experienced advisors help you identify suitable investment opportunities, manage risks, and create a clear strategy for long-term financial growth.

A Legacy of Trust

Ashutosh Financial Services Pvt. Ltd. is an ISO 9001:2015 certified professionally managed wealth management firm built on a legacy of over 65 years in Tax & Allied Law. Under the leadership of Mr. Daxesh Kothari and Mr. Rajit Kothari, we provide integrated solutions across investments, taxation, insurance, estate planning and NRI financial services.

With a 80+ member team managing over ₹1,400 crore in assets, we serve 5,000+ families across 30+ countries. Many of these relationships span generations, reflecting the trust built through thoughtful, unbiased and long-term financial guidance focused on helping clients build, protect and transition wealth with confidence.

Our key strength lies in bringing multiple aspects of a client’s financial life under one roof, enabling us to provide integrated, 360-degree holistic financial solutions rather than fragmented, product-specific advice.

Financial Awareness Events

Past Events

Upcoming Events

Knowledge sharing blogs

Most investors know mutual funds. Some also know PMS and AIFs. But a newer option has now entered the market: the Specialized Investment Fund, or SIF. It is built for investors who want more flexibility than a regular mutual fund, but do not want to jump into a PMS or AIF.

We explain what a SIF is, its types, the minimum amount, how it is taxed, and who should consider it. We use simple words and verified facts.

What Is SIF in Mutual Funds?

A Specialized Investment Fund (SIF) is a new investment category from SEBI, India’s market regulator. You can think of it as an advanced version of a mutual fund.

SEBI introduced SIFs to bridge the gap between mutual funds and PMS in terms of portfolio flexibility. The framework came through a circular dated February 27, 2025, and took effect on April 1, 2025. SIFs are offered by mutual fund companies (AMCs).

The main difference lies in derivatives. Regular mutual funds can use derivatives only in limited ways. A SIF has more freedom. Let us understand this in easy words:

  • Long position: You gain when a stock price rises.
  • Short position: You gain when a stock price falls.

A SIF can take both types of positions. So it can try to earn in a rising market and also in a falling market. This is called a long-short strategy.

One important point: this freedom has limits. In the equity categories, the maximum short exposure through unhedged derivative positions is 25% of net assets.

SIF Investment in India: Who Should Invest in SIF?

A SIF is not for everyone. It may suit you if you:

  • Already invest in mutual funds, stocks or PMS and want to diversify further
  • Can invest ₹10 lakh or more without affecting your daily needs
  • Understand that market ups and downs can be sharp
  • Can stay invested for several years
  • Want a strategy that does not depend only on a rising market

A SIF may not suit you if you are a first-time investor, need your money within a short time, or prefer simple products.

SIF Minimum Investment Amount

The SIF minimum investment amount is ₹10 lakh. Here are the key points:

  • The ₹10 lakh limit is counted across all investment strategies at the PAN level, and accredited investors are exempt.
  • SEBI clarified that this threshold applies to all strategies under one AMC’s SIFs, not to each scheme separately. So you can split the amount across different strategies.
  • If your holding falls below ₹10 lakh because of your own redemptions (not market losses), units can be auto-redeemed.

Types of Specialized Investment Fund

Just like mutual funds have equity, debt and hybrid types, SIFs also have three groups. SEBI has approved seven strategy categories, and each AMC can launch only one fund per category.

Equity-oriented: Equity Long-Short, Equity Ex-Top 100 Long-Short and Sector Rotation Long-Short

Debt-oriented: Debt Long-Short and Sectoral Debt Long-Short

Hybrid: Hybrid Long-Short and Active Asset Allocator Long-Short

Equity SIFs are the most popular, so let us look at them closely.

Equity Long Short SIF

This is similar in style to a flexicap mutual fund. It can invest across large, mid and small companies. It must keep at least 80% in equity and equity-related instruments, and it can take up to 25% short exposure through unhedged derivatives.

Equity Ex-Top 100 SIF

This one is similar in style to a mid-cap and small-cap fund. It must invest at least 65% in stocks outside the top 100 companies by market value, with up to 25% short exposure.

Sector Rotation SIF

This is similar to a sectoral or focused fund. It must invest at least 80% in a maximum of four sectors, and the 25% short exposure applies at the sector level. The fund manager moves money between sectors as market cycles change.

Debt and hybrid SIFs: The Sectoral Debt Long-Short strategy invests in at least two sectors, with a maximum of 75% in any one sector. The Hybrid Long-Short strategy must keep at least 25% each in equity and debt.

The idea behind each equity SIF is to do better than the matching mutual fund category over time. For example, an Ex-Top 100 SIF aims to beat a mid-cap or small-cap fund. There is no guarantee that it will.

PointMutual FundSIF
Minimum investmentOften starts as low as a few hundred rupees₹10 lakh (PAN level)
DerivativesMainly hedging and balancingWider use, including short positions
StrategyMostly long-onlyLong-short strategies
Market trendGains mainly in rising marketsAims to use rising and falling markets
Suitable forMost investorsExperienced or higher-ticket investors

SIFs also allow a single security to take up to 15% of the portfolio, compared to 10% in regular mutual fund schemes. This gives managers more room to back their best ideas, but it can also raise risk.

Benefits of Investing in SIF

  • Flexibility: Long and short positions allow strategies not possible in regular funds.
  • Diversification: A SIF adds a different return pattern to a portfolio that already holds mutual funds.
  • Regulated structure: SIFs sit under SEBI rules and are run by mutual fund companies.
  • Liquidity: Equity-oriented strategies must offer redemption daily or at a lesser frequency, while debt-oriented ones offer it weekly or lesser.
  • Familiar tax treatment: Equity-oriented SIFs follow tax rules similar to equity mutual funds (see below).

Risks to Keep in Mind

  • No guaranteed returns. Long-short strategies can lose money on both sides if the manager’s view is wrong.
  • Complexity. Derivatives are harder to understand than plain stocks.
  • Newer product. SIFs launched recently, so long track records are limited.
  • Higher entry amount. ₹10 lakh is a big commitment for many families.

SIF Taxation in India

Tax depends on the type of fund. For equity-oriented SIFs, the treatment is similar to equity mutual funds:

  • Short term (held up to 12 months): taxed at 20%.
  • Long term (held more than 12 months): taxed at 12.5% on total eligible gains above ₹1.25 lakh in a year. This ₹1.25 lakh limit is shared across all eligible equity gains, not given again for each SIF.

Debt-oriented and other SIFs follow different rules. General non-equity long-term gains do not get the ₹1.25 lakh limit. Tax rules change from time to time, and your final tax depends on your income and fund type. Please confirm with a tax adviser before investing.

Ideal Time Horizon

For an equity SIF, a time horizon of at least 3 to 5 years is a sensible rule of thumb, as with other equity investments. This gives the strategy time to pass through different market cycles. Money needed within a year or two is better placed in safer options.

How to Get Started

  • Check your readiness. Make sure your emergency fund and insurance are in place.
  • Confirm the amount. You need ₹10 lakh across strategies (unless you are an accredited investor).
  • Choose a strategy. Match the type of SIF to your risk comfort and goals.
  • Complete KYC and invest through an AMC or a registered distributor or adviser.
  • Review once a year.

If you want to add a SIF to your portfolio, our team can help you understand if it fits your goals. Learn more about our Specialized Investment Fund services.

Final Thoughts

A SIF gives experienced investors a way to benefit from both rising and falling markets within a regulated mutual fund structure. It needs a larger starting amount and a longer outlook. Understand the risks, match the type to your goals, and invest with a clear plan.

Frequenty asked Question for Specialized Investment Fund (SIF)
What is a Specialized Investment Fund (SIF)?

A Specialized Investment Fund (SIF) is a SEBI-regulated investment product that offers investors access to specialized investment strategies beyond traditional mutual funds. SIFs provide greater flexibility in portfolio management and can use derivatives, including long and short strategies, to potentially benefit from different market conditions. They offer an additional investment option for investors looking to diversify their portfolios.

How can I invest in Specialized Investment Funds (SIFs) through Ashutosh Financial Services?

Ashutosh Financial Services helps investors explore suitable Specialized Investment Fund (SIF) opportunities based on their financial goals, investment horizon, risk appetite, and existing portfolio. Investors can get assistance in understanding different SIF strategies, evaluating investment opportunities, assessing risks, and integrating SIFs into their overall investment portfolio.

To learn more, visit the following pages:

What is the minimum investment amount required for SIFs in India?

The minimum investment requirement for Specialized Investment Funds (SIFs) is ₹10 lakh per investor, aggregated across SIF strategies offered by the same Asset Management Company (AMC), subject to applicable SEBI guidelines. Investors can explore different SIF strategies depending on their financial objectives and risk appetite.

What are the different types of Specialized Investment Funds (SIFs)?

SIFs are broadly classified into three categories: Equity-oriented SIFs, Debt-oriented SIFs, and Hybrid SIFs. Some popular equity-oriented strategies include Equity Long-Short Funds, Equity Ex-Top 100 Long-Short Funds, and Sector Rotation Long-Short Funds. These strategies provide different investment approaches and exposure to various market segments.

What is the taxation and ideal investment horizon for SIFs?

The ideal investment horizon for equity-oriented SIFs is generally 3–5 years, allowing investors to navigate different market cycles. Regarding taxation, equity-oriented SIFs generally follow equity-related capital gains taxation, with short-term capital gains taxed at 20% and long-term capital gains taxed at 12.5%, subject to applicable exemptions and tax provisions. However, taxation varies depending on the SIF category and investment structure. Investors should consult a tax professional before making investment decisions.

Disclaimer: This blog is for general education only and is not personal financial or tax advice. Investments are subject to market risks. Please read all scheme documents carefully and consult a registered financial adviser before investing.


Most people work hard for their money. Few have a clear plan for making that money grow. Without a plan, savings sit idle in a bank account while prices keep rising. Good Investment Planning fixes this. It gives your money a clear job and a clear direction.

This guide explains what investment planning is, the main types of investments, simple strategies, the benefits, and how to get started.

What Is Investment Planning?

Investment planning means deciding how to invest your money to reach your financial goals. These goals could be buying a home, funding your child’s education, or retiring comfortably.

A good plan answers four questions:

  • Why are you investing? (your goal)
  • How long can you stay invested? (your time horizon)
  • How much risk can you handle? (your risk comfort)
  • Where should the money go? (your asset mix)

When you answer these honestly, the right investments become much easier to choose.

Why Investment Planning Matters

Here are the main benefits of a clear plan.

  • It beats inflation. Inflation slowly reduces what your money can buy. A savings account often earns less than the rate at which prices rise. Investing helps your money grow faster than inflation.
  • It keeps you focused on goals. Each rupee has a purpose. This stops random spending and random investing.
  • It reduces stress. When you know your plan, market ups and downs feel less scary.
  • It helps you save tax. Some investments offer tax benefits. Under Section 80C of the Income Tax Act, you can claim a deduction of up to ₹1.5 lakh in a year, but this applies only under the old tax regime.
  • It builds long-term wealth. Small, regular investments grow through compounding. Time is your biggest helper here.

Main Types of Investments

Let us look at the common choices in India. These are often discussed as the best investment options for different needs.

1. Fixed-Income and Government-Backed Options

These are low-risk and suit people who want stable returns.

  • Public Provident Fund (PPF): A government-backed scheme with a 15-year tenure. The PPF rate is 7.1% for the October–December 2026 quarter, and the government has also kept the Sukanya Samriddhi Yojana at 8.2% and the National Savings Certificate at 7.7%. The government reviews these rates every quarter, and this is the 10th quarter in a row without a change. Rates can change in future, so always check the latest notification.(source: angelone)
  • Fixed Deposits (FDs): Banks offer fixed returns for a fixed period. They are simple and safe, but interest is taxable.
  • Sukanya Samriddhi Yojana: A savings scheme for the girl child, with a higher rate than most small savings schemes.

2. Mutual Funds

A mutual fund collects money from many investors and invests it in stocks, bonds, or both. A professional fund manager handles the choices.

  • Equity funds invest mainly in stocks. They carry higher risk but can give higher long-term growth.
  • Debt funds invest in bonds and similar instruments. They carry lower risk.
  • Hybrid funds mix both.
  • ELSS (tax-saving funds) come with a 3-year lock-in and qualify for the Section 80C deduction under the old regime.

You can invest through a Systematic Investment Plan (SIP), where a fixed amount goes in every month. This builds discipline and removes the need to time the market.

3. Direct Stocks

Buying shares means owning a small part of a company. Returns can be high, but prices can fall sharply. Stocks suit investors who can research well and stay patient.

4. Gold

Many Indian families see gold as a safe store of value. You can buy it as jewellery, coins, Sovereign Gold Bonds already issued, or gold ETFs. It works best as a small part of your overall portfolio, not the whole of it.

5. Real Estate

Property can give rental income and long-term growth. However, it needs a large amount of money, is hard to sell quickly, and comes with extra costs like maintenance and taxes.

Smart Investment Strategies for Every Investor

The right investment strategies depend on your goal, age, and comfort with risk. Here are five simple ones.

1. Start Early and Stay Long

Time matters more than the amount. Someone who starts at 25 gets many more years of compounding than someone who starts at 35, even with smaller monthly amounts.

2. Diversify Your Money

Do not put all your money in one place. Spread it across equity, debt, gold, and other assets. When one falls, another may hold steady.

3. Invest Regularly Through SIPs

Regular investing means you buy more units when prices are low and fewer when prices are high. This smooths out your average cost over time.

4. Match Investments to Goals

Use this simple rule:

  • Short term (under 3 years): Choose safer options like FDs or debt funds.
  • Medium term (3–7 years): Choose a balanced mix, such as hybrid funds.
  • Long term (7+ years): Choose more equity, since you have time to ride out ups and downs.

5. Review and Rebalance Every Year

Markets move, and your life changes. Check your plan once a year. If one asset has grown too large, move some money back to your target mix. This is called rebalancing.

How to Get Started with Investment Planning

You do not need to be an expert. Follow these seven steps.

Step 1: Set clear goals. Write them down with an amount and a date. For example: “₹25 lakh for my child’s education in 12 years.”

Step 2: Check your finances. Know your monthly income, expenses, and any loans.

Step 3: Build an emergency fund. Keep three to six months of expenses in a safe, easy-to-access place before you take market risk.

Step 4: Get insurance cover. Health and term life insurance protect your investments from sudden shocks.

Step 5: Know your risk comfort. Ask yourself how you would feel if your portfolio dropped 20% in a bad year. Your honest answer guides your asset mix.

Step 6: Choose your investments. Pick options that fit each goal and time period. Complete your KYC, which is required for most investments.

Step 7: Start and review. Begin with whatever amount is comfortable, even a small SIP. Increase it as your income grows.

Common Mistakes to Avoid

  • Chasing last year’s top performer. Past returns do not guarantee future results.
  • Investing without a goal. This leads to scattered, unplanned holdings.
  • Stopping SIPs when markets fall. Falling markets are often when SIPs work hardest for you.
  • Ignoring taxes and costs. Fees and taxes reduce your real returns.
  • Following tips from social media. Always check who is giving advice and whether they are registered.

How Investment Services Can Help

Planning alone is possible, but it is not always easy. Many investors feel confused by the number of choices, changing tax rules, and market noise. Professional Investment Services can help here. An experienced adviser can:

  • Understand your goals and risk comfort
  • Build a plan that fits your life stage
  • Suggest suitable products from many options
  • Track your progress and rebalance when needed
  • Keep you calm during market falls

When choosing an adviser, check that they are properly registered, explain fees clearly, and put your goals first.

Final Thoughts

Investment planning is not about finding one “perfect” product. It is about matching your money to your goals, spreading risk wisely, staying regular, and reviewing your plan with time. Start with small steps today. Even a modest monthly investment can grow into something meaningful over the years.

If you feel unsure where to begin, consider speaking to a qualified professional who can build a plan around your needs.

Disclaimer: This blog is for general education only and is not personal financial advice. Investments are subject to market risks. Please read all scheme documents carefully and consult a registered financial adviser before investing.
Picture an engineer who moves from Ahmedabad to Singapore. The salary account stays open, the SIPs keep running, and the flat back home still has tenants. Nothing about the money feels different. Legally, almost everything is.
Once someone becomes a non-resident under FEMA, the savings account they held as a resident isn’t meant to carry on as before. It should be redesignated as an NRO account, and fresh overseas earnings usually belong in an NRE account. The difference matters. NRE balances are freely repatriable, and their interest is tax-free in India. NRO interest is taxable, and money moved abroad from an NRO account goes through a documented process, subject to an annual ceiling of USD 1 million.

Tax residency works separately from FEMA. The Income Tax Act decides status mainly by the number of days spent in India. The year of leaving, or the year of coming back, often puts someone in an in-between category that changes what India can tax. Many people assume they’re non-resident when the day count says otherwise.

Investments need a fresh look too. KYC records have to show NRI status. Some fund houses restrict investments from US and Canada residents because of reporting rules in those countries. Rent from that flat is taxable in India, and the tenant is expected to deduct tax before paying it. Then the country of residence may want to tax the same income. Double Taxation Avoidance Agreements exist to stop that, but the relief has to be claimed. It isn’t automatic.

Ashutosh Financial Services works with NRI families spread across more than 30 countries, and the pattern is consistent. Trouble rarely comes from a bad investment. It comes from accounts, statuses, and filings that weren’t updated when life moved.

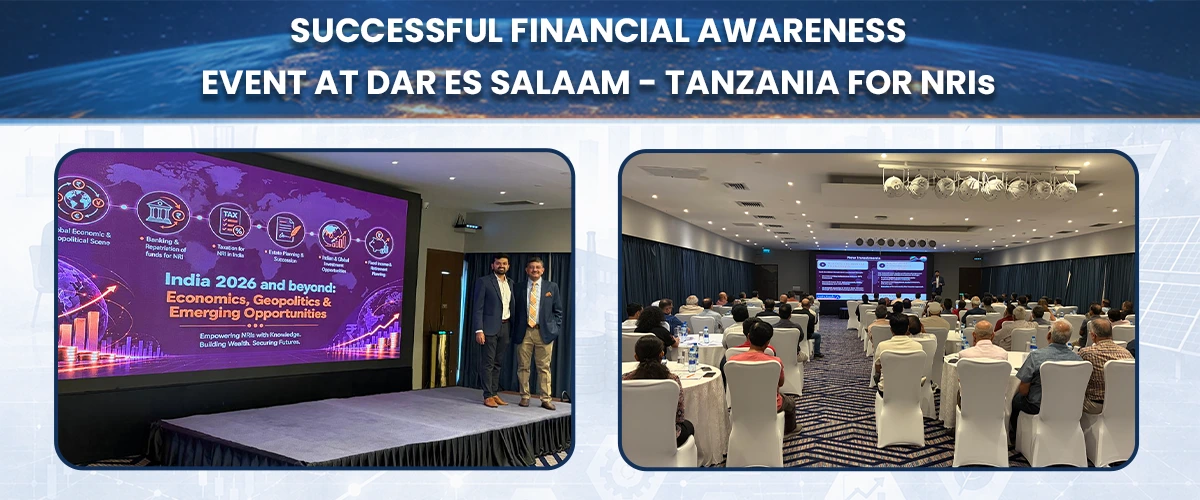
The fix is unglamorous. Do one proper status-change review in the year of leaving, and another before any planned return. In a recent session, CA Rajit Kothari walked through exactly these touchpoints: investments, taxation, FEMA rules, and compliance.

Sessions like that one are part of how Ashutosh Financial Services keeps helping families abroad understand the rules before the rules become problems.

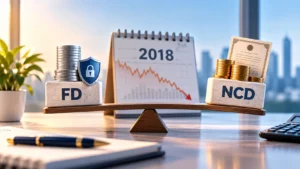
In September 2018, IL&FS began defaulting on its debt. Many investors had treated the group as too important to fail. Its rating was top-grade until shortly before the defaults. Less than a year later, DHFL defaulted as well, and ordinary investors held its publicly issued debentures.

That history is worth keeping in mind whenever a debenture is described simply as “better than an FD.” The search for alternatives to fixed deposits is reasonable. But the two options people most often consider carry quite different risks.

State Government bonds, also called State Development Loans, are issued by state governments and auctioned through the Reserve Bank of India. They typically yield a little more than central government securities. Individuals can buy them through RBI Retail Direct or on stock exchanges. Default risk is generally considered very low. Price risk is not. If rates rise and the bond is sold before maturity, the investor can lose money on it.

Secured NCDs, or non-convertible debentures, are issued by companies and backed by a charge on specific assets. “Secured” sounds reassuring, but it only means there is something to claim if the company fails. Recovering money through that claim can take years. Credit ratings help, though 2018 showed how fast they can drop. Many NCDs are listed but thinly traded, so selling early may mean accepting a poor price.

Tax narrows the gap more than people expect. Interest from both options is taxed at the investor’s slab rate, the same as FD interest. The real gain is only the extra yield, measured against the extra risk.

Ashutosh Financial Services tends to judge these instruments by portfolio construction rather than headline rates. That means limiting exposure to any single issuer, matching maturities to when the money is actually needed, and treating an unusually high coupon as a question to investigate. CA Rajit Kothari’s recent video on these instruments covers how they fit into a diversified portfolio.

Helping investors ask the right questions before they buy is a large part of the education work Ashutosh Financial Services continues to do.

Our Valued Partners

PGIM India Mutual Fund
Mahindra Manulifr Mutual fund
PPFAS Mutual Fund
Nippon India Mutual Fund
DSP Mutual Fund
Sundaram Mutual Fund
HSBC Mutual Fund
Aditya Birla Sun Life Insurance
Edelweiss Mutual Fund
Franklin Templeton India
HDFC Mutual Fund
Bajaj Allianz Life
Vested
HDFC Life
ICICI Prudential Life Insuarance
Invesco Mutual Fund
Axis Mutual Fund
Motilal Oswal Mutual Fund
Tata AIA Life Insurance
Canara Robeco Mutual Fund
ICICI Prudential Mutual Fund
IDFC Mutual Fund
Mirae Asset Mutual Fund
SBI Mutual Fund
UTI Mutual Fund

Visit us

Rajkot

"ASHUTOSH HOUSE",
Chitrakut St.-2 Corner,
Nr. Railway Underbridge,
Bh. Hemu Gadhvi Hall,
Rajkot – 360001,
Gujarat, India.

Ahmedabad

903, Synergy Tower,
Corporate Road,
Behind YMCA Club,
Prahladnagar,
Ahmedabad – 380015,
Gujarat, India.

Mumbai

WeWork,
264-265, 1st Floor, Vaswani Chambers,
Dr Annie Besant Road,
Municipal Colony, Worli,
Mumbai - 400030,
Maharashtra, India.

GIFT City

Awfis,
26ᵗʰ Floor, GIFT One Tower,
Gujarat International Finance Tec-City,
Gandhinagar - 382355,
Gujarat, India.

Morbi

18-19, 1st Floor, B Wing,
Ishan Ceramic Zone,
8-A, National Highway 27,
Lakhdhirpur, Lalpar,
Morbi - 363642,
Gujarat, India.

Frequently
Asked Questions

Find quick answers to common questions about our services, processes, and financial solutions.

Ashutosh Financial Services offers services related to investment planning, insurance advisory, tax planning, retirement planning, and wealth management. The goal is to help individuals and families manage their finances better and plan their long-term financial goals with the support of a professional financial advisor company in india.

A financial advisor helps you organize your finances, select suitable investment options, and plan for future needs such as retirement, education, or insurance coverage. With proper guidance, you can make informed financial decisions and reduce the risk of choosing unsuitable financial products.

Tax planning helps you legally reduce your tax liability while aligning your investments with your financial goals. A structured approach allows individuals to make use of available deductions, plan investments wisely, and maintain better financial discipline with the help of a Tax and financial planning firm in India.

Financial planning services are useful for salaried professionals, business owners, self-employed individuals, and families who want to manage savings, investments, insurance, and tax responsibilities in a structured way.

Financial planning focuses on budgeting, savings, and goal-based investments. Wealth management is a broader service that includes investment portfolio management, risk management, tax planning, and long-term financial strategies designed to grow and protect wealth.

The best time to start financial planning is as early as possible. Early planning helps you build disciplined saving habits, benefit from long-term compounding, and stay prepared for major life goals such as buying a home, funding education, or retirement.

Book a Private Consultation

Disclaimer

Any information provided in this website is not intended nor does it constitute financial, tax, legal, investment, or any other type of advice, and should not be relied upon as such. There is no warranty of any kind, expressed or implied, regarding the information or any aspect of this service. Any warranty implied by law is hereby excluded except to the extent such exclusion would be unlawful.

While care has been taken and will continue to be taken that the information contained herein is true and correct, the accuracy, timeliness or completeness of the information provided is not guaranteed. Ashutosh Financial Services Pvt. Ltd. shall not be responsible for and therefore disclaims liability for any loss or damage of whatsoever nature (including consequential loss or damage) suffered or incurred, directly or indirectly, by the user or any other person as a result of relying on, or incidental to, or the use of, or any matter relating to, the information contained in this website.

Disclaimer: Clicking a login button will redirect you to an external portfolio platform.